


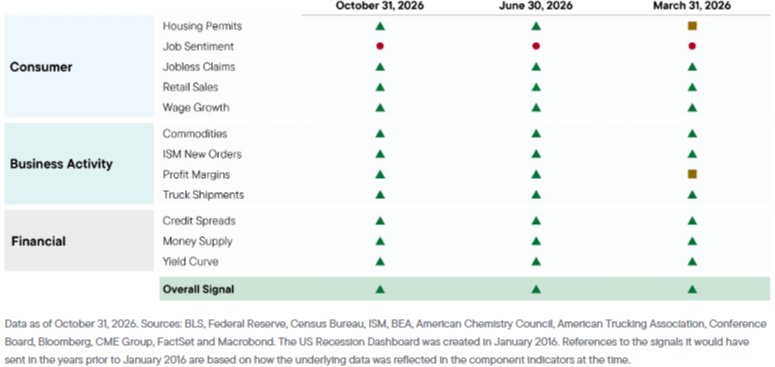
The big picture beats politics. Election Day has markets watching how divided Washington will be over the coming years. Below is a summary of the most recent Recession Indicators Report:
Key Takeaways:
- According to Jeff Schulze, CFA, Head of Economics & Market Strategy with ClearBridge Investments:
- Election Results Matter Less Than Congressional Margins: Narrow majorities could lead to political gridlock and uncertainty, while larger majorities may create opportunities for bipartisan spending agreements.
- History Favors Stocks Following Midterm Elections: Since 1950, the S&P 500 Index has averaged a 15.1% gain in the 12 months following midterms, with positive returns in all 19 periods studied. Past performance does not guarantee future results.
- Economic Growth Remains Strong: Third-quarter GDP expanded at a 3.4% annualized rate, supported by business investment, artificial intelligence infrastructure spending, and resilient consumer activity.
- Corporate Earnings Continue to Impress: S&P 500 earnings are on track to grow approximately 30% year-over-year, providing fundamental support for stock prices beyond political developments.
- Recession Risk Appears Relatively Low: With 11 of 12 recession indicators signaling expansion, the analysis estimates just a 15% probability of recession over the next 12 months.
- Focus on Fundamentals, Not Politics: While election outcomes may create short-term volatility, strong economic growth, rising corporate profits, and favorable historical market trends provide reasons for optimism heading into 2027.
Bottom Line: Political uncertainty may influence short-term market movements, but economic growth and corporate earnings remain the more important drivers of long-term investment performance.
ClearBridge U.S. Recession Dashboard
Source: ClearBridge Investments
Market Volatility Following the Midterm Elections: Keeping Perspective
After the midterm elections, U.S. stock markets experienced one of their sharpest declines of 2026 as investors reacted to the election results and their potential implications for the technology sector. Concerns about increased regulation of artificial intelligence (AI) and data centers added pressure to an already vulnerable area of the market. The S&P 500 Index declined 4.36% for the day, while the Nasdaq-100 Index fell more than 6%.
While declines of this magnitude can certainly be unsettling, it is important to remember that market volatility surrounding midterm elections is not unusual, and short-term uncertainty does not necessarily translate into long-term weakness.
Why Midterm Elections Can Create Market Uncertainty
Historically, midterm elections have tended to favor the political party not occupying the White House. This often creates uncertainty surrounding Congressional leadership, future legislation, and the direction of government policy.
Financial markets generally prefer predictability, so the possibility of significant policy changes can lead to short-term volatility as investors reassess expectations. However, history suggests that changes in the political landscape, while sometimes disruptive in the near term, have rarely prevented stocks from delivering positive returns over longer periods.
What History Tells Us About Post-Midterm Market Performance
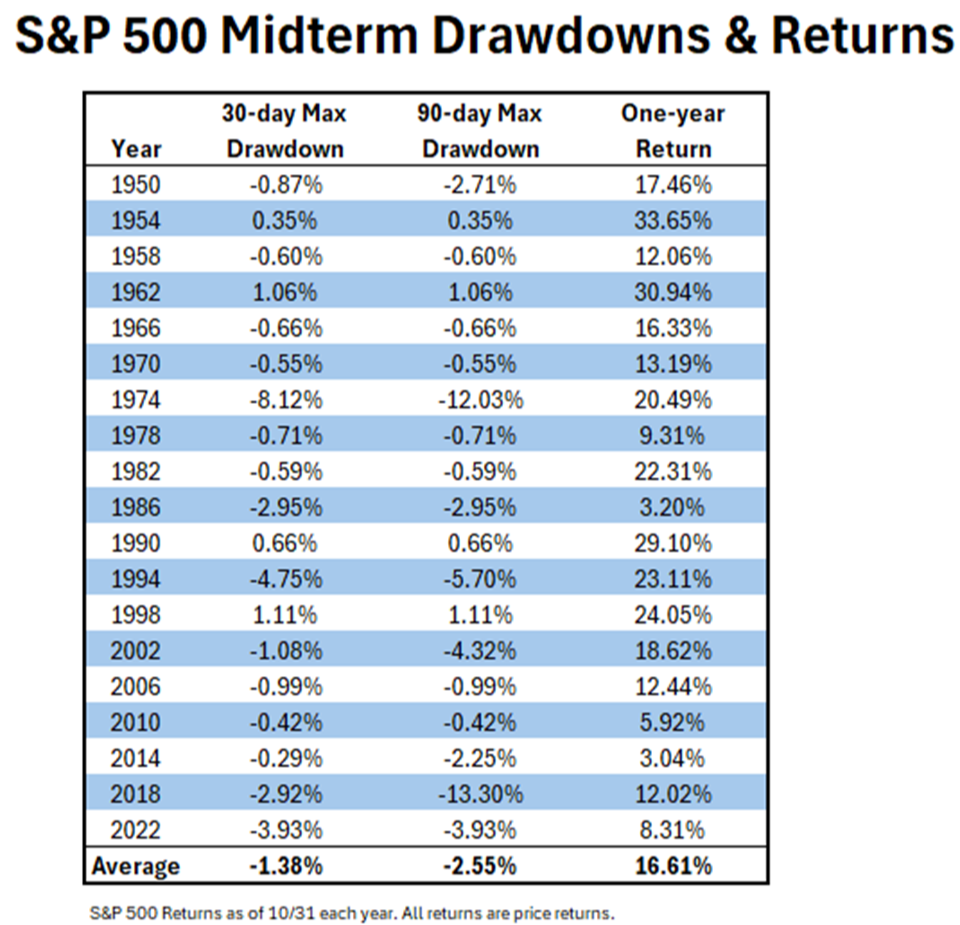
Looking at S&P 500 Index performance surrounding midterm elections since 1950 provides some valuable perspective.
The accompanying table examines the largest market declines during the 30- and 90-day periods following October 31 of each midterm election year, along with the market's performance over the subsequent 12 months.
Source: Nasdaq Dorsey Wright
The historical data highlights two important observations:
- Short-term declines are common. Market pullbacks following midterm elections have occurred frequently and, in some cases, have been substantial. In 2018, for example, the S&P 500 declined more than 13% during the following three months.
- Longer-term results have historically been encouraging. In every midterm election period included in the analysis, the S&P 500 was higher one year later, with an average gain of nearly 17%. For comparison, the index's average annual return since 1950 has been approximately 9.4%.
These historical results illustrate an important distinction: Short-term market volatility and long-term investment performance are not necessarily connected in the way investors might initially expect.
Looking Beyond the Headlines
Of course, historical performance does not guarantee future results. There is no assurance that stocks will produce similar gains over the coming year, or even that returns will be positive.
Additionally, the technology sector, particularly companies associated with artificial intelligence, had already begun showing signs of weakness before the election. These underlying concerns deserve attention, and we will continue monitoring their potential impact on the broader market.
Nevertheless, the historical evidence offers a reason to maintain perspective. Market declines surrounding political transitions are not uncommon, and periods of heightened uncertainty have frequently been followed by meaningful recoveries.
The View from Main Stree
At Main Street Wealth Advisors, we believe that successful investing requires maintaining perspective during both favorable and challenging market environments.
Although the recent sell-off was significant, a single difficult trading session does not necessarily signal a lasting change in the market's longer-term direction. Political headlines, policy uncertainty, and shifting investor sentiment can create temporary disruptions, but economic fundamentals, corporate earnings, and broader market trends remain important drivers of long-term performance.
Rather than allowing short-term volatility to dictate investment decisions, we believe investors are generally better served by remaining focused on their financial objectives, maintaining appropriate diversification, and following a disciplined investment strategy.
The takeaway: Midterm elections may introduce uncertainty, but history reminds us that periods of market turbulence can be temporary. While we remain attentive to developing risks, the recent decline alone does not provide sufficient reason to abandon a well-considered long-term investment plan.
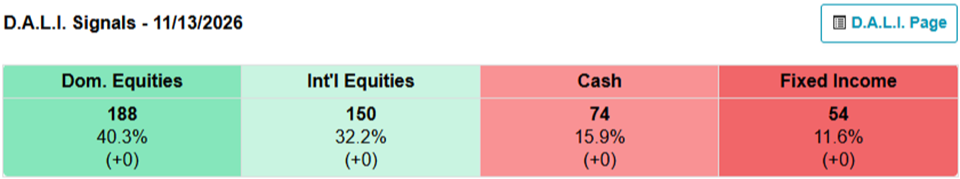
Below is the most recent D.A.L.I. (Dynamic Asset Level Investing) Indicator showing Domestic Equities and International Equities in the top two positions, while Cash and Fixed Income remain far behind.
Source: Nasdaq Dorsey Wright
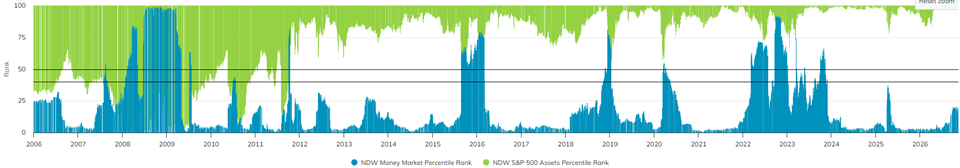
The current reading for the PR4050 Cash Trigger is: U.S. Equity Core = 98.59% & Money Market = 19.72%. For the PR4050 indicator to trigger and alert us when we should consider moving to cash, U.S. Equity Core must be 40% or below and Money Market must be 50% or above.
Source: Nasdaq Dorsey Wright
P.S. If you believe this information would be of benefit to anyone you know, please share this communication with them. Also, if you, or someone you know, would like to be added to the weekly market update, please click here to provide us with the e-mail address.
Main Street Wealth Advisors
33801 1st Way South, Suite 271
Federal Way, WA 98003
Office: (253) 944-1047
Fax: (253) 944-1075
ART-1208871
Securities and advisory services offered through LPL Financial, a Registered Investment Advisor, Member FINRA/SIPC.
These views are those of the author, not of the broker-dealer or its affiliates. This material contains an assessment of the market and economic environment at a specific point in time and is not intended to be a forecast of future events, or a guarantee of future results. All investments involve risk, including loss of principal. Forward-looking statements are subject to certain risks and uncertainties. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. All indices are unmanaged and may not be invested into directly.
Technical analysis is based on the study of historical price movements and past trend patterns. There is no assurance that these movements or trends can or will be duplicated in the future. Nasdaq Dorsey Wright developed the indicators described above. They have been prepared without regard to any particular investor's investment objectives, financial situation, and needs. Accordingly, investors should not act on any recommendation (express or implied) or information in this report without obtaining specific advice from their financial advisors and should not rely on information herein as the primary basis for their investment decisions.
Nasdaq Dorsey Wright’s “DALI" employs relative strength-based analysis to rank macro asset classes based on developing leadership trends within the global capital markets. The objective guidance within DALI provides the tools necessary to properly allocate portfolios across all major asset classes in an effort to emphasize strength wherever it exists. Domestic Equities, International Equities, Commodities, Currencies, Fixed Income and Cash are evaluated daily to identify dynamic developments across investment genres, as well as within them. This tool provides the tactical precision that allows investors to adapt as the market leadership changes.
International investing involves special risks such as currency fluctuation and political instability and may not be suitable for all investors. These risks are often heightened for investments in emerging markets.
This material is for general information only and is not intended to provide specific advice or recommendations for any individual. There is no assurance that the views or strategies discussed are suitable for all investors or will yield positive outcomes. Investing involves risks including possible loss of principal. Any economic forecasts set forth may not develop as predicted and are subject to change.
The NASDAQ Composite Index measures all NASDAQ domestic and non-U.S. based common stocks listed on The NASDAQ Stock Market. The market value, the last sale price multiplied by total shares outstanding, is calculated throughout the trading day, and is related to the total value of the Index.
The S&P 500® Index: A free-float capitalization-weighted index published since 1957 of the prices of 500 large-cap common stocks actively traded in the United States. The stocks included in the S&P 500® are those of large publicly held companies that trade on either of the two largest American stock market exchanges: the New York Stock Exchange and the NASDAQ.
MSCI World Index: A broad global equity index that represents large and mid-cap equity performance across 23 developed markets countries.
Bonds are subject to market and interest rate risk if sold prior to maturity. Bond values will decline as interest rates rise and bonds are subject to availability and change in price.