


September and Q3 2026 are now officially behind us. The Stock Trader’s Almanac says, “September is when leaves and stocks tend to fall; on Wall Street, it’s the worst month of all,” reflecting the negative reputation that September has developed with investors over the years. This year, September was unkind to most stocks as the S&P 500 Equal Weight Index finished the month down more than 5.5%. However, strong showings from some of the biggest stocks—especially semiconductors—cushioned the capitalization-weighted S&P 500, which finished the month down just 0.78%. Meanwhile, the Nasdaq-100, which is heavily weighted toward large tech stocks, finished September up more than 3%.
For the quarter, the S&P 500 posted a gain of just over 2%, while the equal-weight index was down 2.3%. Although it fell during Q3, Technology once again leads the Domestic Equity (U.S. stocks) sector rankings in our Dynamic Asset Level Investing (DALI) tool followed by Healthcare and Communication Services. DALI provides us with a heatmap of where relative strength (and weakness) lies across and within the major asset classes.
International Equities have outperformed U.S. stocks for most of 2026, but that trend shifted in Q3 as the MSCI Emerging Markets Index fell around 1% and the MSCI EAFE Index, which comprises developed international markets, eked out a gain of 0.30%. A strengthening U.S. dollar was a headwind for non-U.S. assets as the U.S. Dollar Index reached its highest level of 2026 late in the quarter. As of the end of September, despite underperforming in Q3, International Equities remain at the top of the DALI asset class rankings with Domestic Equities a close second.
U.S. Treasury yields surged in September with the 10-year U.S. Treasury Yield Index breaching the 5% level for the first time since 2007. The rise in yields has driven considerable weakness in core U.S. fixed income. Meanwhile, non-U.S. fixed income, which had been an area of strength for much of the last year, was hampered by strength in the U.S. dollar. Q3 also saw the Federal Reserve raise the federal funds rate for the first time since 2023 and the market is currently predicting a better than 85% chance of another increase by the end of the year.
Renewed tension in the Middle East helped drive a 30% surge in oil prices in Q3. Meanwhile crack spreads, which gauge the profit generated by refining oil into gasoline, diesel, and distillates, sit near all-time highs. Both factors have helped drive worries about inflation and have been cited as contributing to the rise in interest rates. Gold and silver advanced in August but gave back most of the gains in September as surging yields were a major headwind for precious metals.
With the beginning of October, we enter what has historically been one of the more volatile months for the market. Some of the more notorious market meltdowns have occurred or accelerated in October including 1978 (-9%), 1987 (-22%), and 2008 (-17%). However, the S&P 500 has been positive in October more often that it has been negative and the month is sometimes referred to as the "bear killer," as its end ushers in the beginning of the seasonally strong six months of the year.
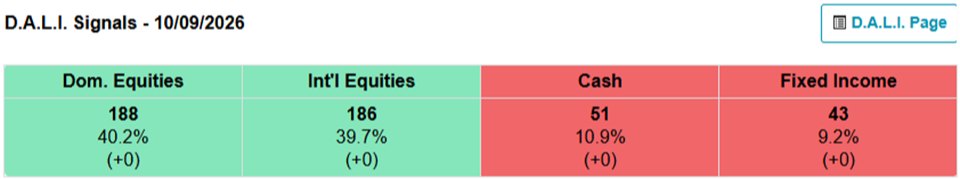
Below is the most recent D.A.L.I. (Dynamic Asset Level Investing) Indicator showing Domestic Equities and International Equities battling for the top spot, while Cash and Fixed Income remain far behind.
Source: Nasdaq Dorsey Wright
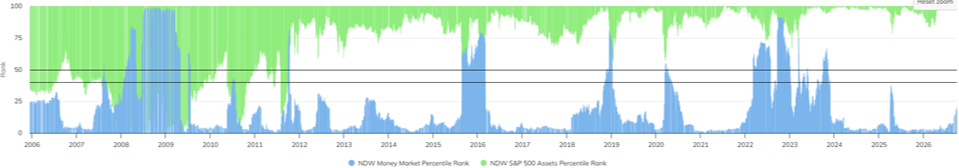
The current reading for the PR4050 Cash Trigger is: U.S. Equity Core = 99.30% & Money Market = 19.72%. For the PR4050 indicator to trigger and alert us when we should consider moving to cash, U.S. Equity Core must be 40% or below and Money Market must be 50% or above.
Source: Nasdaq Dorsey Wright
P.S. If you believe this information would be of benefit to anyone you know, please share this communication with them. Also, if you, or someone you know, would like to be added to the weekly market update, please click here to provide us with the e-mail address.
Main Street Wealth Advisors
33801 1st Way South, Suite 271
Federal Way, WA 98003
Office: (253) 944-1047
Fax: (253) 944-1075
ART-1189864
Securities and advisory services offered through LPL Financial, a Registered Investment Advisor, Member FINRA/SIPC
These views are those of the author, not of the broker-dealer or its affiliates. This material contains an assessment of the market and economic environment at a specific point in time and is not intended to be a forecast of future events, or a guarantee of future results. All investments involve risk, including loss of principal. Forward-looking statements are subject to certain risks and uncertainties. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. All indices are unmanaged and may not be invested into directly.
Technical analysis is based on the study of historical price movements and past trend patterns. There is no assurance that these movements or trends can or will be duplicated in the future. Nasdaq Dorsey Wright developed the indicators described above. They have been prepared without regard to any particular investor's investment objectives, financial situation, and needs. Accordingly, investors should not act on any recommendation (express or implied) or information in this report without obtaining specific advice from their financial advisors and should not rely on information herein as the primary basis for their investment decisions.
Nasdaq Dorsey Wright’s “DALI" employs relative strength-based analysis to rank macro asset classes based on developing leadership trends within the global capital markets. The objective guidance within DALI provides the tools necessary to properly allocate portfolios across all major asset classes in an effort to emphasize strength wherever it exists. Domestic Equities, International Equities, Commodities, Currencies, Fixed Income and Cash are evaluated daily to identify dynamic developments across investment genres, as well as within them. This tool provides the tactical precision that allows investors to adapt as the market leadership changes.
International investing involves special risks such as currency fluctuation and political instability and may not be suitable for all investors. These risks are often heightened for investments in emerging markets.
This material is for general information only and is not intended to provide specific advice or recommendations for any individual. There is no assurance that the views or strategies discussed are suitable for all investors or will yield positive outcomes. Investing involves risks including possible loss of principal. Any economic forecasts set forth may not develop as predicted and are subject to change.
The NASDAQ Composite Index measures all NASDAQ domestic and non-U.S. based common stocks listed on The NASDAQ Stock Market. The market value, the last sale price multiplied by total shares outstanding, is calculated throughout the trading day, and is related to the total value of the Index.
The S&P 500® Index: A free-float capitalization-weighted index published since 1957 of the prices of 500 large-cap common stocks actively traded in the United States. The stocks included in the S&P 500® are those of large publicly held companies that trade on either of the two largest American stock market exchanges: the New York Stock Exchange and the NASDAQ.
MSCI World Index: A broad global equity index that represents large and mid-cap equity performance across 23 developed markets countries
Bonds are subject to market and interest rate risk if sold prior to maturity. Bond values will decline as interest rates rise and bonds are subject to availability and change in price.